FairRate Canada facts and media assets
Verified background, approved descriptions, downloadable images, methodology, and contact information for journalists, editors, newsletter writers, and researchers.
At a glance
What it is
An independent educational comparison and reporting product, free for borrowers, for Canadian homeowners reviewing a supported 3-year or 5-year fixed mortgage renewal offer.
What it is not
Not a lender, mortgage broker, mortgage agent, brokerage, marketplace, law firm, financial advisor, or mortgage underwriter.
Business model
Free checker; optional paid reports (CA$24 Rate Fairness Report and CA$49 Full Renewal Decision Report); and optional broker introductions, made only with the borrower’s consent, that may earn FairRate a referral fee. Results never depend on it.
Current support
Canadian 3-year fixed and 5-year fixed renewal offers. Each offer is compared only with public same-term fixed context. Other terms and variable-rate offers are not supported by the benchmark-backed checker.
Approved company descriptions
One sentence
FairRate Canada is an independent, free resource that helps Canadian homeowners place a supported 3-year fixed or 5-year fixed mortgage renewal offer beside dated public market context before signing.
Long description
FairRate Canada provides a free initial check and optional written educational reports for supported Canadian 3-year and 5-year fixed mortgage renewal offers. It compares the homeowner’s stated offer with fresh public Canadian same-term fixed context when a usable source is available, then explains scheduled-payment context and questions to review before signing. FairRate is free for borrowers and does not arrange mortgages. If a borrower chooses to be introduced to a mortgage broker, FairRate may earn a referral fee; it always asks first, and results never depend on it.
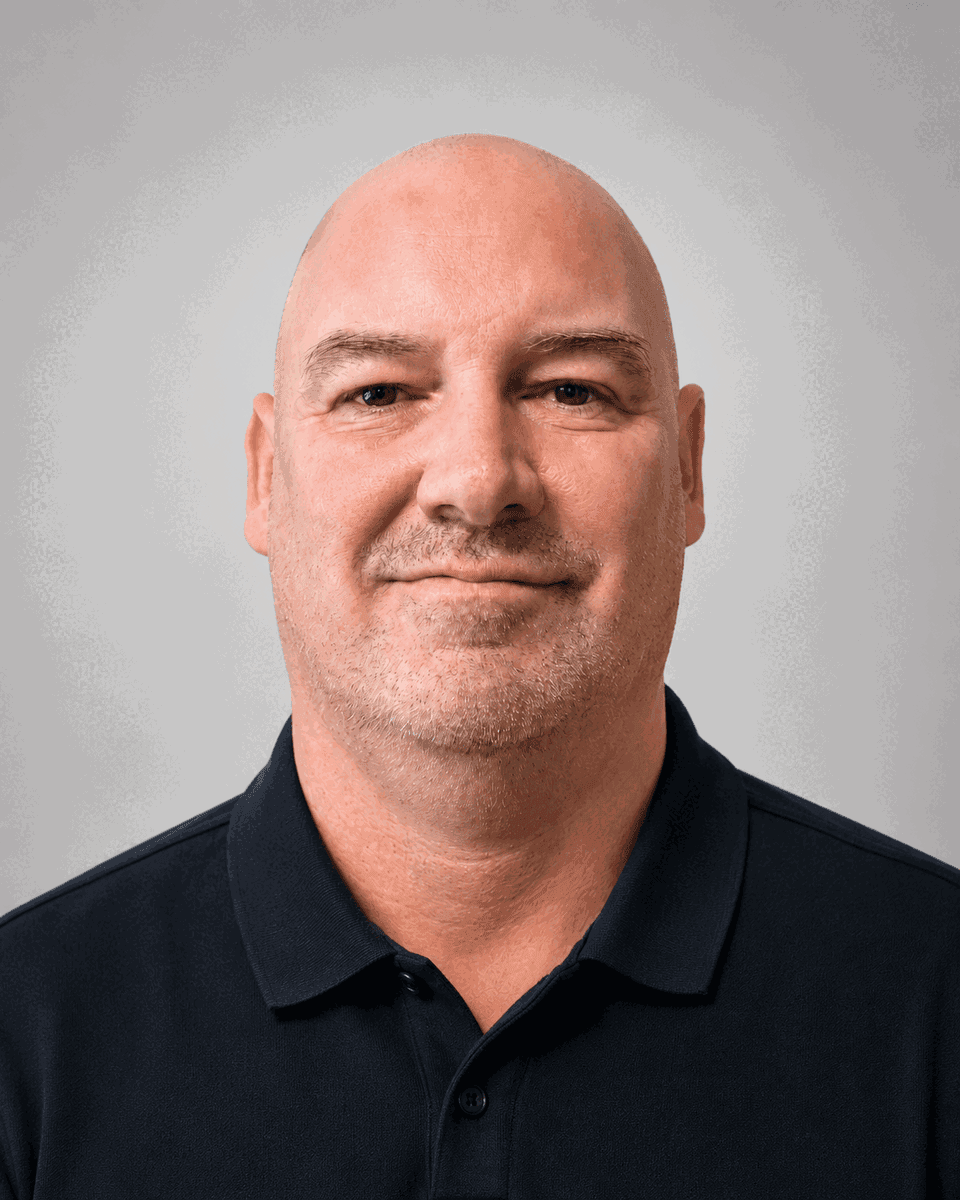
Founder
Andy Atchison
Andy Atchison lives in Edmonton, Alberta, and is the founder and operator of FairRate Canada, an independent resource helping Canadian homeowners understand supported mortgage renewal offers and compare them with dated public market context. Free checks have optional paid reports and do not authorize a broker introduction.
Andy is presented as FairRate Canada’s founder and operator—not as a mortgage broker, mortgage agent, financial advisor, or provider of borrower-specific mortgage advice.
Downloadable media assets
Approved for editorial use about FairRate Canada. Image credit: FairRate Canada.
Evidence brief · checked September 12, 2026
What reporters can say now
Why a written renewal offer merits review
A renewal is a decision point involving the offered rate, term, payment frequency, fees, product features, and switching considerations. FairRate helps a homeowner place a written 3-year or 5-year fixed offer beside dated public same-term comparison context and identify questions to review before signing. It does not prove another rate is available or recommend accepting, negotiating, or switching.
How to describe the benchmark
Use the value and “as of” date shown on the live methodology page. Describe it as public Canadian same-term fixed comparison context—not a lender offer, market average, approval, or guaranteed available rate. Preserve the term, source, and freshness limitations.
External 2026 renewal context
CMHC reported on May 20, 2026 that 35% of surveyed recent mortgage consumers who had renewed said interest-rate changes increased their financial pressure, with their mortgage payments increasing by an average of CA$375 per month.
Source: CMHC 2026 Mortgage Consumer Survey, released May 20, 2026. The survey was conducted in January 2026 among more than 4,100 recent mortgage consumers who had renewed, refinanced, or purchased in the prior 18 months. CMHC's release does not state the renewal-only subsample size. This is external survey context—not FairRate proprietary data—and should not be generalized to all Canadian homeowners.
Current original-data status
The Mortgage Renewal Offer Index is a research pilot collecting voluntary submissions. Consult its live status and publication rules before quoting findings. It should not be described as a national renewal-offer average or lender ranking.
View live index status and publication rules →Federal renewal-statement and consumer guidance is available from the Financial Consumer Agency of Canada.
Original-data rule
FairRate Canada does not publish headline Mortgage Renewal Offer Index findings before reaching at least 25 valid, privacy-safe submissions. Any eventual findings must be described as a voluntary, non-representative sample—not as a picture of all Canadian homeowners or verified lender rate sheets.
Useful links for writers
How to cite FairRate Canada
Use the exact page title, FairRate Canada as publisher, the specific supporting URL and your access date. When citing a comparison rate, retain its term, source date, eligibility context and limitations.
Example: FairRate Canada. “FairRate Canada Methodology.” Updated [page date]. Accessed [access date]. https://www.fairratecanada.ca/methodology
Describe future offer-index findings as voluntary and non-representative. Retain the sample size, collection period, supported offer type and methodology link. Submitted offers are not rates paid or verified lender rate sheets. Describe Andy Atchison as founder and operator.
Media contact
Include your publication, topic, deadline, and the specific fact or asset you need.
andy@fairratecanada.caDisclosure
FairRate Canada provides educational comparison context. It does not arrange mortgages, take applications, approve credit, negotiate with lenders, guarantee another rate or savings, or provide personalized financial advice. Public comparison context is not a lender quote, approval, or guarantee that a displayed rate is available to a particular borrower.